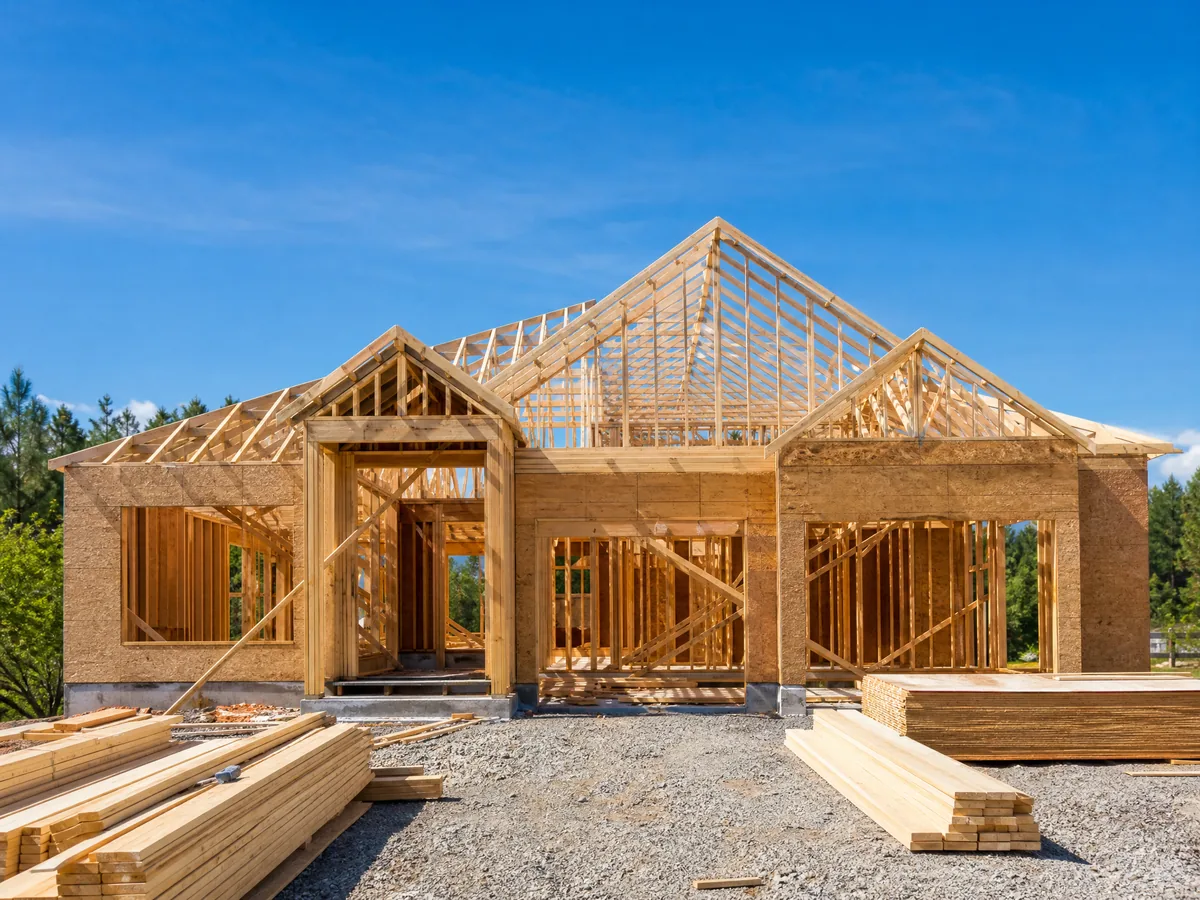
Ground up construction loans for Georgia builders, dirt to finish.
Built for spec home builders and developers. We fund the land and the vertical build up to 70% LTV and 85% of cost, with draws that keep pace with the job. A Georgia construction note structured inside 62 months escapes the state's tax on long-term notes. Business-purpose only, and every structure is set in underwriting.
Typical figures, subject to underwriting and market conditions. Not a commitment to lend.
How it works
We finance both the land and the vertical construction, with a draw schedule built around your timeline. Experienced builders can access higher leverage on cost.
Does a Georgia construction loan pay the intangible recording tax?
Not if the note stays inside 62 months, and most do. O.C.G.A. 48-6-61 taxes an instrument securing a long-term note at $1.50 per $500 of face amount, about 0.30 percent. The definition in 48-6-60(3), as amended by HB 586 effective July 1, 2025, makes a note long-term only when part of the principal falls due more than 62 months from the date of the note or the security instrument. A 12 to 24 month build pays zero. So does the common commercial structure of a 3-year construction loan with one or two 1-year extension options, which now fits inside the line. For scale, a $2,000,000 note that did run long-term would carry $6,000 (2,000,000 / 500 = 4,000 units x $1.50 = $6,000). Structure the term deliberately and have your closing attorney confirm it. Subject to underwriting.
What does a Georgia closing add to a construction file?
An attorney on both ends, and no remote signing. In re UPL Advisory Opinion 2003-2 approved the State Bar committee's view that a non-attorney preparing and facilitating the execution of a deed of conveyance is the unauthorized practice of law, that it cannot be delegated to a non-lawyer, and that a Georgia attorney must be physically present at the closing. The attorney also holds and disburses funds, so there is no separate escrow company in the chain. Georgia has no remote online notarization for its own notaries, pandemic-era authority having lapsed in 2022, so a builder closing a lot purchase, a construction loan, and later a sale to an end buyer is scheduling three in-person events. Line the firm up before the lot goes under contract. Confirm the current position with your closing attorney.
What does the tax bill do to a Georgia spec build while I carry it?
Land is assessed the same way as everything else, and the finished house resets. O.C.G.A. 48-5-7(a) assesses all taxable tangible property at 40 percent of fair market value, taxed on the county millage, so the effective rate is millage x 0.40: ten mills on a $300,000 lot is $1,200 (300,000 x 0.40 x 0.010 = 1,200). Your lot purchase price caps value for the next taxable year under 48-5-2(3), which helps in year one, but that cap is a one-year rule and the vertical build is exactly the "substantial addition or improvement" that lets assessors move a value under the 48-5-299(c)(4) exception after a visual on-site inspection. Underwrite the carry on the improved value rather than the dirt bill. Your annual notice comes no later than July 1 and the written appeal deadline is 45 days from the notice date. Take the numbers to your Georgia CPA.
How do I insure a Georgia build if carriers will not write it?
Through the residual market, with an agent. The Georgia Underwriting Association describes itself as functioning "as a residual insurance market in order that basic property and liability insurance may be made available to all Georgians," and writes dwelling, homeowners, mobile home and commercial property. It does not sell direct; a licensed agent submits the application. That is the fallback for a property under construction or sitting vacant that private carriers decline. On pricing generally, Georgia is a 45-day prior-filing state under O.C.G.A. 33-9-21: for lines other than personal private passenger auto an insurer must file rates and underwriting rules with the Commissioner at least 45 days before the effective date, and no premium may be collected under a filing that did not arrive 45 days ahead. Get a bound quote on the actual address before you set the budget.
How much of a Georgia build will you fund, and what do I bring?
Up to 70% of value and 85% of cost, so plan on 15% of cost from you. On a $2,000,000 total project cost that is up to $1,700,000 from us and $300,000 from you (2,000,000 x 85% = 1,700,000), with the loan also held to 70% LTV against the completed value, whichever binds first. Money comes out in draws against the build schedule, not in one advance. Terms run 12 to 24 months and loan sizes go up to $5,000,000. Add the attorney's closing fee and the 0.10 percent Georgia transfer tax on the lot purchase. Subject to underwriting.
What credit do you need for a Georgia construction loan?
There is no minimum score on this program. Construction is asset-based, so we run credit but it carries far less weight than it would at a bank. The file turns on the budget, the schedule, the completed value, and your builder. Weaker credit is usually answered with lower leverage rather than a decline, and there is no hard credit pull to start. Subject to underwriting.
Does my track record change my leverage on a Georgia build?
Yes. Experienced builders can access higher leverage. A builder with completed Georgia projects, a real schedule, and subs who have worked together before will price and lever better than a first build, and the difference shows up in leverage rather than in a yes or no. Bring the completed-project list, the budget line by line, and the draw schedule you expect. For what the metro is absorbing, see Atlanta ground up construction. Subject to underwriting.
More Ground-Up Construction questions, answered on the program page
Local rules move. Every tax rate, fee, ordinance and market figure here comes from a primary source and carries the date we read it, and we correct them as the rules change. Where a number is mid-change or we could not verify it, we say so rather than guess. Before you commit a budget, confirm anything that drives it with the city or county, and talk to your attorney or CPA on questions of law or tax.
Published by USA Mortgage Funding, LLC, NMLS #152588. Researched from primary sources by our team, drafted with AI assistance, and every figure checked against its source before publishing. Where an answer rests on a public record, that record is linked under it. Figures read on 2026-08-23.
Funding Georgia deals fast.
Get real terms, usually same day. No obligation, no hard credit pull to start.