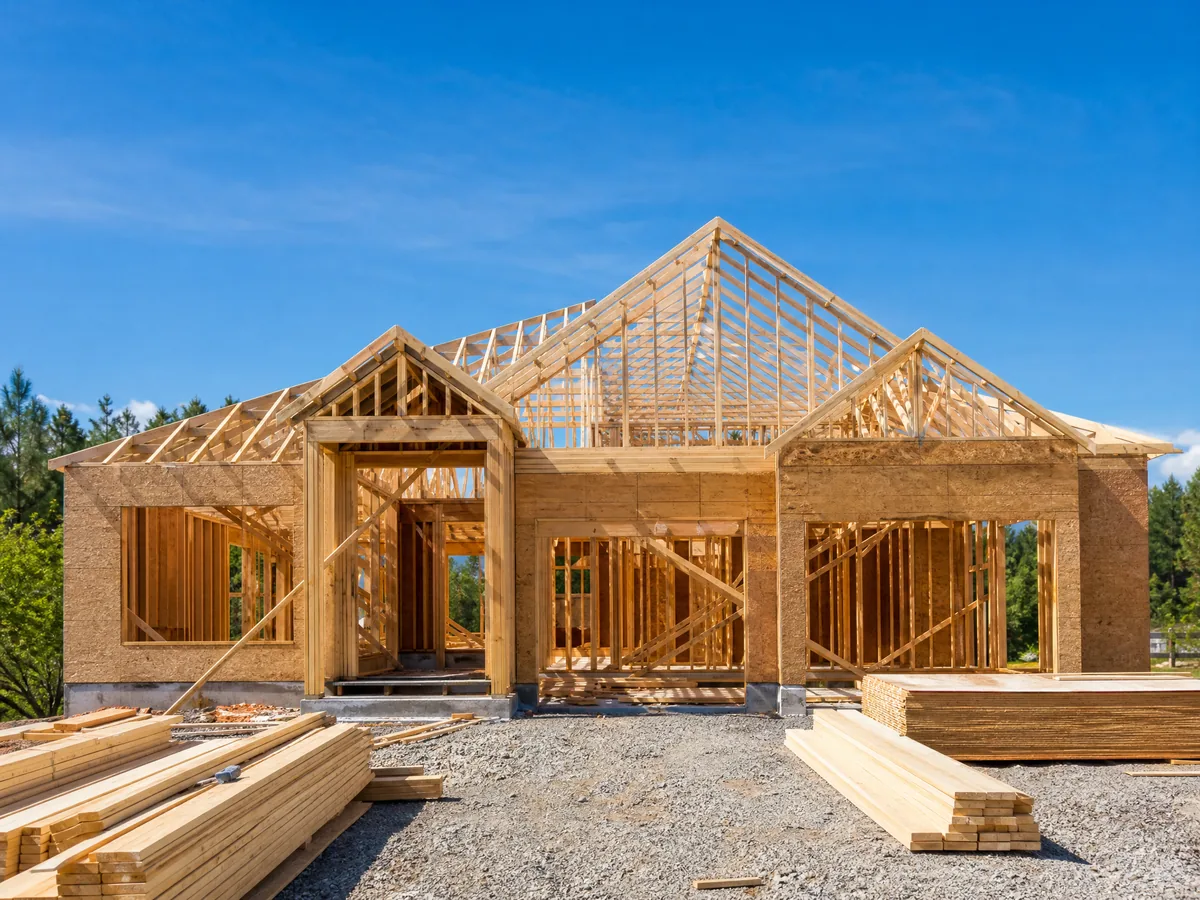
Construction financing for Florida infill and spec builds.
Land and vertical construction funded on one facility, drawn against your build schedule. Up to 70% of value or 85% of cost, on a 12 to 24 month term. Florida taxes the construction mortgage at recording and assesses the dirt while you build, so both belong in the pro forma. Business-purpose only, and every structure is set in underwriting.
Typical figures, subject to underwriting and market conditions. Not a commitment to lend.
How it works
We finance both the land and the vertical construction, with a draw schedule built around your timeline. Experienced builders can access higher leverage on cost.
What does Florida charge to record a construction mortgage?
0.55 percent of the loan, at recording, with no cap. Mortgage stamps run 35 cents per $100 of indebtedness under section 201.08, and the nonrecurring intangible tax adds 2 mills on the secured obligation under section 199.133. On a $2,000,000 Florida construction facility that is $11,000 due at closing (2,000,000 x 0.55% = 11,000). Two things builders get wrong. First, the widely repeated $2,450 doc-stamp cap sits in section 201.08(1)(a) and covers notes, not recorded mortgages, so a large construction mortgage pays the full rate. Second, the tax is on the instrument, not on time or on funds drawn, so a facility you only partly draw still paid tax on the recorded amount. Size the facility to the build, and add deed stamps of 0.7 percent on the land purchase separately.
How is my Florida land taxed while I am building?
As nonhomestead residential property, cap and all, and reset to just value the year after you bought it. Section 193.1554 covers residential property with nine or fewer dwelling units including vacant residentially zoned land, capping annual reassessment increases at 10 percent, but only for levies other than school district levies. The cap resets on any sale or transfer of legal or beneficial title, so your first full year of ownership is assessed at just value with no carryover from the seller. Then, as the vertical goes up, the improvement adds value that the cap does not shelter. On a 12 to 24 month build that is two assessment dates, each January 1, and the second one prices a house rather than a lot. Model both, and watch for the TRIM notice, because the Value Adjustment Board petition is due within 25 days of its mailing.
Does business purpose keep a Florida construction loan outside state lending law?
No, and that is a Florida-specific answer. Section 494.001(25) has three limbs and only the first is a purpose test. Limb (b) reaches a loan on commercial real property where the borrower is an individual or the lender is a noninstitutional investor, and limb (c) reaches improved property of five or more dwelling units the same way, neither asking what the proceeds are for. If you are building a small multifamily project, limb (c) is squarely in view. Section 494.0025(4)(d) also makes it a prohibited practice to misrepresent a residential mortgage loan as a business purpose loan, so document the intended use and the intended exit at the start. Our licensing is handled. Your part is short: title the project in an entity, and have your attorney confirm the structure before you record anything.
What happens if a Florida build goes sideways and the lender has to foreclose?
It goes to court, because Florida is judicial for everything. Chapter 702 governs commercial and investment property with no power-of-sale alternative, so the process runs materially slower than a deed-of-trust state. We will not publish a Florida day count, because no reliable series exists. What we will say is that the mechanics favour a lender at the end rather than the start: under section 45.0315 the borrower may cure only until the certificate of sale is filed or the date the judgment sets, and otherwise there is no right of redemption at all. Section 702.10 also gives an order-to-show-cause fast track aimed at non-owner-occupied property. For a builder, the practical read is that a stalled Florida project is expensive to unwind for everyone, which is why we underwrite the schedule and the contractor as hard as the value.
Does the balloon-mortgage legend apply to a construction loan?
Usually not, and it is worth knowing why. Section 697.05 requires a conspicuous balloon legend on a Florida mortgage whose final payment exceeds twice a regular periodic payment, at the top of page one and above the mortgagor's signature. Omitting it automatically extends the maturity date until paid, prepayable without penalty, which is the worst outcome a short-term lender can have. Subsection (4) exempts first mortgages, interest-only mortgages with principal due at maturity, terms of five years or more, and credit exceeding $500,000. A first-position construction facility is exempt on more than one ground. The exposure case is a second-position Florida loan under $500,000 with amortising payments and a short balloon, which is not how we write construction debt. Subject to underwriting.
Where in Florida does new construction pencil?
That is a metro question, not a state one, and the metro pages carry it. Land cost, absorption, impact fees, and insurance load are local; the tax and title regime is not. For build conditions and comps, read Orlando ground up construction, Tampa, Jacksonville, or Fort Myers. The statewide constants you carry into any of them are the 0.55 percent recording tax on the facility, the January 1 assessment date, and a title premium that section 627.782 fixes across the state so that shopping carriers on price does not work. Bring the site plan, the budget, and the draw schedule and we will size it.
What credit score do I need for a Florida construction loan?
There is no minimum score on this program. Construction is asset-based, so credit is run but carries far less weight than it would at a bank. The file turns on the site, the budget, the schedule, and the finished value. Weaker credit is usually answered with lower leverage rather than a decline, and there is no hard credit pull to start. Subject to underwriting.
How much equity do I need in a Florida ground up deal?
Enough to clear both leverage tests, whichever binds first. We fund up to 70% of value and up to 85% of cost, up to $5,000,000. On a project with $2,000,000 of total cost, 85% LTC is $1,700,000 from us and $300,000 from you (2,000,000 x 85% = 1,700,000), provided that also sits inside 70% of finished value. Funds release as draws against the build schedule, not up front, on a 12 to 24 month term. Add the 0.55 percent Florida recording tax on the facility. Subject to underwriting.
Can a first-time builder get a Florida construction loan?
Experience moves the leverage rather than the answer.Experienced builders can access higher leverage on this program, so a thinner record generally means less of the 70% of value and 85% of cost, not a decline. Bring the general contractor's licence and record, a real line-item budget, and a draw schedule that matches the permit path. Title the project in an entity. Subject to underwriting.
More Ground-Up Construction questions, answered on the program page
Local rules move. Every tax rate, fee, ordinance and market figure here comes from a primary source and carries the date we read it, and we correct them as the rules change. Where a number is mid-change or we could not verify it, we say so rather than guess. Before you commit a budget, confirm anything that drives it with the city or county, and talk to your attorney or CPA on questions of law or tax.
Published by USA Mortgage Funding, LLC, NMLS #152588. Researched from primary sources by our team, drafted with AI assistance, and every figure checked against its source before publishing. Where an answer rests on a public record, that record is linked under it. Figures read on 2026-08-23.
Funding Florida deals fast.
Get real terms, usually same day. No obligation, no hard credit pull to start.