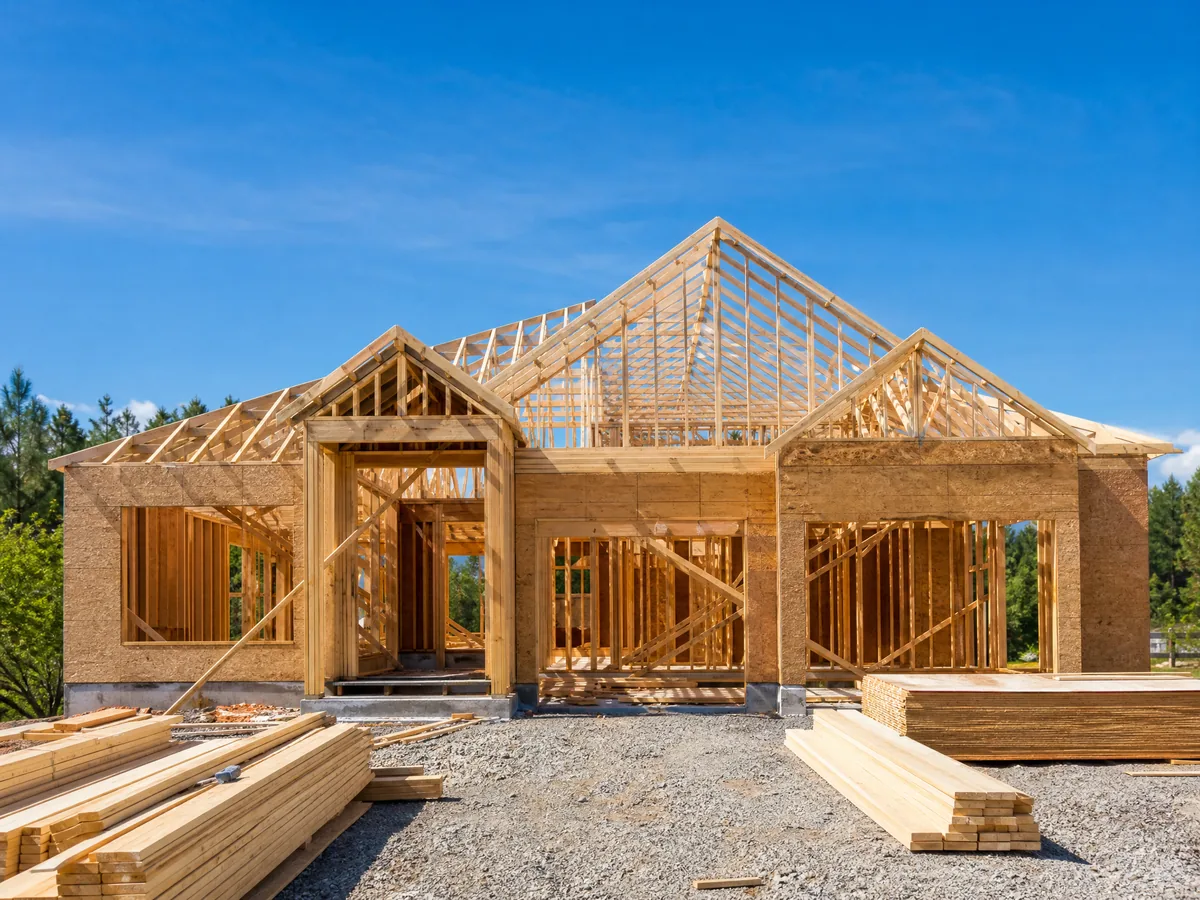
Ground up construction loans that back Sacramento new builds.
Built for spec home builders and developers. We fund the land and the vertical build up to 70% LTV and 85% of cost, with draws that keep pace with the job. Levee accreditation, not the property itself, decides what your flood zone requires and what insurance costs on a Sacramento build. Business-purpose only, and every structure is set in underwriting.
Typical figures, subject to underwriting and market conditions. Not a commitment to lend.
How it works
We finance both the land and the vertical construction, with a draw schedule built around your timeline. Experienced builders can access higher leverage on cost.
How does levee accreditation affect insurance and permitting on a Sacramento ground-up build?
The levee segment protecting your parcel, not the parcel itself, sets the flood zone that drives your insurance and construction requirements. Sacramento sits at the confluence of the Sacramento and American rivers behind an engineered levee system, and the Corps withdrew accreditation on segments outside the Natomas Basin because they no longer meet urban levee standards. Where a segment carries Zone A99, the parcel sits in a Special Flood Hazard Area, which triggers the federal mandatory purchase requirement on any federally backed loan, though A99 does relax construction requirements relative to Zone AE and generally prices below other A zones. On our business-purpose loans, flood insurance is a matter of our own credit policy, not a federal mandate, so get the flood determination before you buy the lot and put the premium in the build budget before the deal is priced.
Could a Sacramento construction project get stuck in permit limbo the way Natomas did before?
It has happened here, and that is why levee status is a live diligence item, not paperwork. Natomas went without new construction permits for roughly seven years, from 2008, when FEMA remapped the basin into the high-risk floodplain after a Corps re-evaluation of the levees, until 2015, when FEMA remapped it to Zone A99 and permitting resumed. Congress authorized reconstructing 42 miles of Natomas levees in 2014, work toward a 200-year level of protection continues, and FEMA updates maps by Letter of Map Revision as segments get certified, so parcels in the same neighborhood can carry different zones. Confirm the accreditation status of the specific levee segment protecting your lot before you count on a permit timeline.
Is Sacramento actually building new homes, or is this a stalled-permit metro?
It is a working homebuilding market, unlike most Western metros where permits collapsed. The Sacramento-Roseville-Folsom area authorized 7,626 new single-family units in 2025, and the first half of 2026 was tracking near the 2024 pace. That is about 17% below the 2021 peak of 9,161 but still above 2019 and 2020 levels, a real supply story that does not depend on a shortage narrative.
Will my new subdivision lot carry a tax bill older homes in the neighborhood do not have?
Likely yes, if the subdivision was built after 1990, and it is not a tax that fades over time. Community Facilities Districts formed under the Mello-Roos Act levy a special tax on a formula set by the district, not on assessed value, so Proposition 13's 1% ceiling and 2% growth cap do not touch it, and it survives the sale to the next owner. These districts cluster in North Natomas, Elk Grove, Folsom, Rancho Cordova and Lincoln, the metro's newer suburbs. No verified dollar amount exists for any named Sacramento district, so check the parcel for a CFD special tax and pull the actual figure before you underwrite the deal.
What happens to my new build's tax bill the moment it is finished or sells?
The county resets the assessed value to what you paid or what the new construction is worth, and the difference arrives on its own bill. Because a sale or new construction is a change in ownership or an assessable event, Sacramento County's assessor issues a supplemental assessment outside the normal secured roll cycle, and it must be appealed within 60 days of the bill's mailing date, not on the regular calendar. Underwrite the tax line off the price paid or the completed value, never off a seller's old assessment, since Proposition 13's 2% annual cap means a long-held comparable's listed tax bill understates what you will actually owe.
Once the build is done, does a Sacramento rental actually cash flow?
The rent trend is moving the right direction for a hold. Metro-wide, Zillow's observed rent index rose 2.0% year over year while home values fell 1.3%, so coverage is improving mechanically, and the City of Sacramento itself posts the strongest gross yield of the metro's major submarkets at 5.15%. That is a gross figure with no expense data behind it, and Sacramento's expense line, from Mello-Roos to flood insurance, is the whole story, so underwrite it before you commit to a build-to-rent exit into a DSCR rental loan.
How much of a Sacramento build do I have to fund myself?
About 15% of total cost, and the loan is also capped at 70% of value. We fund the land and the vertical build to up to 85% of cost and up to 70% LTV, whichever is lower. On a $1,000,000 Sacramento project cost that is up to $850,000 from us and $150,000 from you (1,000,000 x 85% = 850,000), with draws released against the build schedule. Put the flood premium and any Mello-Roos line in the budget before the deal is priced, not after. Subject to underwriting.
What credit score do I need for a Sacramento construction loan?
There is no minimum score on this program. We run credit, but a ground-up loan is underwritten on the land, the budget, and the build, so credit carries far less weight here than at a bank. Weaker credit is usually offset with lower leverage rather than a decline, which on a Sacramento build means more of the cost comes from you. There is no hard credit pull to start. Subject to underwriting.
Do I need to be an experienced builder to get a Sacramento construction loan?
No, but experience moves your leverage. Experienced builders can access higher leverage inside the 70% LTV and 85% LTC ceilings; a first project generally prices lower. That matters in a metro that kept building through the cycle, with 7,626 new single-family units authorized in 2025, because you are competing for lots and subs against builders who do this every year. Terms run 12 to 24 months with draws on the schedule. Subject to underwriting.
More Ground-Up Construction questions, answered on the program page
Local rules move. Every tax rate, fee, ordinance and market figure here comes from a primary source and carries the date we read it, and we correct them as the rules change. Where a number is mid-change or we could not verify it, we say so rather than guess. Before you commit a budget, confirm anything that drives it with the city or county, and talk to your attorney or CPA on questions of law or tax.
Published by USA Mortgage Funding, LLC, NMLS #152588. Researched from primary sources by our team, drafted with AI assistance, and every figure checked against its source before publishing. Where an answer rests on a public record, that record is linked under it. Figures read on 2026-08-15.
Funding Sacramento deals fast.
Get real terms, usually same day. No obligation, no hard credit pull to start.