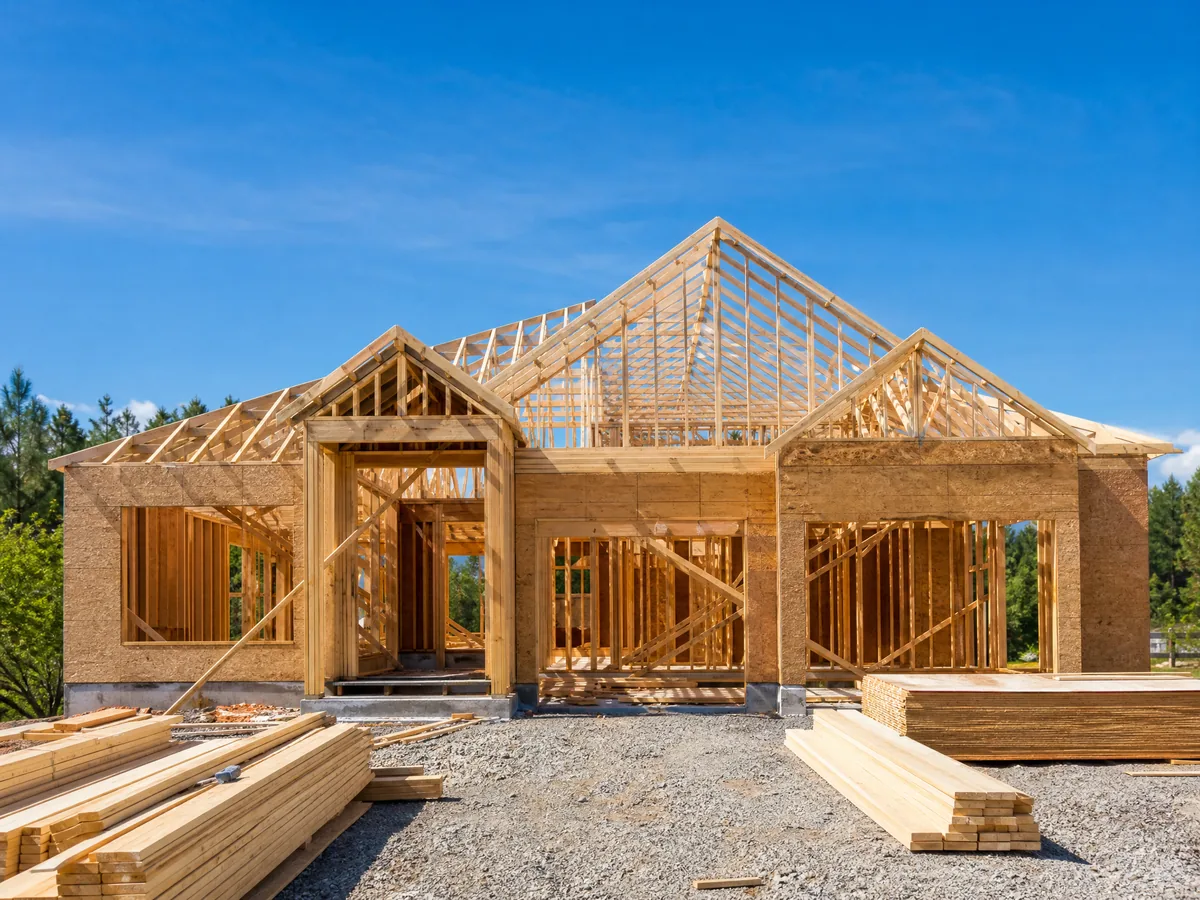
Ground up construction loans for Oklahoma builders.
Land, vertical, and the carry to finish, funded up to $5M with draws released against your build schedule. Oklahoma's mortgage registration tax rewards short construction paper, and an open-ended loan amount is a tax hazard here, so the maximum belongs in the instrument. Business-purpose only, and every structure is set in underwriting.
Typical figures, subject to underwriting and market conditions. Not a commitment to lend.
How it works
We finance both the land and the vertical construction, with a draw schedule built around your timeline. Experienced builders can access higher leverage on cost.
Why does my Oklahoma construction mortgage need to state a maximum amount?
Because of how the mortgage registration tax treats an open-ended instrument. Title 68 section 1906 says that where the principal is not determinable from the instrument, the mortgage is taxed on the value of the property as determined by the county treasurer, unless the owner files a sworn statement of the maximum amount secured. On a construction file, where the balance rises with each draw, that is not a hypothetical. State the maximum in the mortgage, or file the sworn statement. A related rule under section 1905 works in your favor: supplemental instruments, corrective mortgages and spreader mortgages are not retaxed unless they create new or further indebtedness, and claiming that treatment requires a sworn statement with the county treasurer. Have Oklahoma counsel handle both.
What does a 12 to 24 month construction term do to the mortgage tax?
It keeps it near the bottom of the table. Title 68 section 1904 scales the tax to term: 2 cents per $100 under two years, 4 cents at two to three years, and up to 10 cents at five years or more. A 12-month or 18-month construction mortgage sits in the 0.02% band, so a $1,000,000 facility carries $200 (1,000,000 / 100 = 10,000 units, x $0.02 = $200), plus the $10 county treasurer certification fee. Cross the 24-month line and the rate doubles to 0.04%. It is a small number, but it is a real reason to set the term deliberately rather than by habit. Section 1907 is the part to respect: an unpaid mortgage tax means the instrument cannot be recorded and cannot be foreclosed.
What does Oklahoma charge me on the lot purchase?
The documentary stamp tax, at 75 cents for each $500 of consideration under title 68 section 3201, which is 0.15% of price. On a $60,000 lot that is $90 (60,000 / 500 = 120, x $0.75 = $90). Recording is flat statewide under title 28 section 32: $8 for the first page, $2 per additional page, plus $10 per instrument for records preservation. One Oklahoma quirk worth passing to whoever drafts your documents: a nonconforming instrument costs $25 for the first page and $10 per additional page under the same section, because margins and formatting are prescribed. On a construction file with a long mortgage and a set of exhibits, that difference is not nothing.
Does the 5% valuation cap protect me while I build?
No. Article 10 section 8B caps annual increases in fair cash value at 5% on all locally assessed real property, which is broader than the homestead-only caps some states use, but the same section carves out two situations: the cap does not apply in a year when title is transferred, and the increased value attributable to improvements is assessed at fair cash value in the year the improvements are made. Ground up construction triggers both. So budget the tax line at the completed value of the house or building, not at the raw-land bill you inherit at closing. The cap starts working for whoever holds the finished asset, which is one reason a build-to-rent exit and a DSCR rental loan pencil differently from a build-to-sell.
How does Oklahoma foreclosure practice shape a construction loan?
It makes the document set matter more than the calendar promises. Oklahoma is judicial by default, and the power of sale under title 46 sections 40 to 49 is available only if the mortgage carries the bold, underlined legend that section 43 prescribes, followed by a 35-day notice of intention to foreclose and a notice of sale served at least 30 days out and published weekly for four weeks. There is also a trade-off that generic content usually misses. Under title 46 section 4 and title 12 section 760, a mortgage that waives appraisement cannot have an order of sale issue for six months after judgment, while a mortgage that does not waive it goes faster but cannot sell below two-thirds of the appraised value. Neither of us wants to use any of this, but it is why the paperwork on an Oklahoma build is written the way it is.
What insurance should I expect to carry during an Oklahoma build?
Builder's risk, and a bigger number than in most states. Oklahoma is reported as the most expensive homeowners insurance market in the country in 2025 coverage of a LendingTree analysis, and we are deliberately not publishing an average premium because the circulating figures disagree and none is a regulator number. The primary data the Insurance Department does publish points to a calmer 2026: 64 homeowners rate changes in the first seven months of 2026, averaging plus 3.25%, with individual carriers filing anywhere from minus 15.0% to plus 19.7%. Quote the specific project with a real agent, and quote it early, because a coverage gap on a partially framed structure is the one exposure that can end a build.
What credit score do I need for an Oklahoma construction loan?
There is no minimum score on this program. Construction is asset-based, so the file turns on the land basis, the budget, the schedule and the finished value. We run credit, but it carries far less weight than it would at a bank, and weaker credit is usually answered with lower leverage rather than a decline. There is no hard credit pull to start. Subject to underwriting.
How much do I need to put into an Oklahoma build?
Enough to clear both tests. We fund up to 70% of value and up to 85% of cost, and the tighter of the two governs. On a $1,000,000 completed value with a $900,000 total cost, the value test allows $700,000 (1,000,000 x 70% = 700,000) and the cost test allows $765,000 (900,000 x 85% = 765,000), so $700,000 is the number and $200,000 of cost is yours. Loans run to $5,000,000 on 12 to 24 month terms with draws released against your build schedule. Experienced builders can access higher leverage. Subject to underwriting.
More Ground-Up Construction questions, answered on the program page
Local rules move. Every tax rate, fee, ordinance and market figure here comes from a primary source and carries the date we read it, and we correct them as the rules change. Where a number is mid-change or we could not verify it, we say so rather than guess. Before you commit a budget, confirm anything that drives it with the city or county, and talk to your attorney or CPA on questions of law or tax.
Published by USA Mortgage Funding, LLC, NMLS #152588. Researched from primary sources by our team, drafted with AI assistance, and every figure checked against its source before publishing. Where an answer rests on a public record, that record is linked under it. Figures read on 2026-08-12.
Funding Oklahoma deals fast.
Get real terms, usually same day. No obligation, no hard credit pull to start.