
Direct private lending in most states
Call us anytime at 512-617-9400
Apply now
Program 03

Ground-Up Construction in Stockton

Ground up construction loans for Stockton spec builders and rebuilds.

Ground-up construction funds spec builds and teardown rebuilds up to 70% of value and 85% of cost, with a draw schedule paced to your build. San Joaquin County's single-family permits fell 33.2% in 2025 even as the county kept growing, so new supply here stays thin. Building on land in a mapped flood hazard zone in this valley also means clearing a state flood-protection finding before ground breaks. This is business-purpose lending only, subject to underwriting.
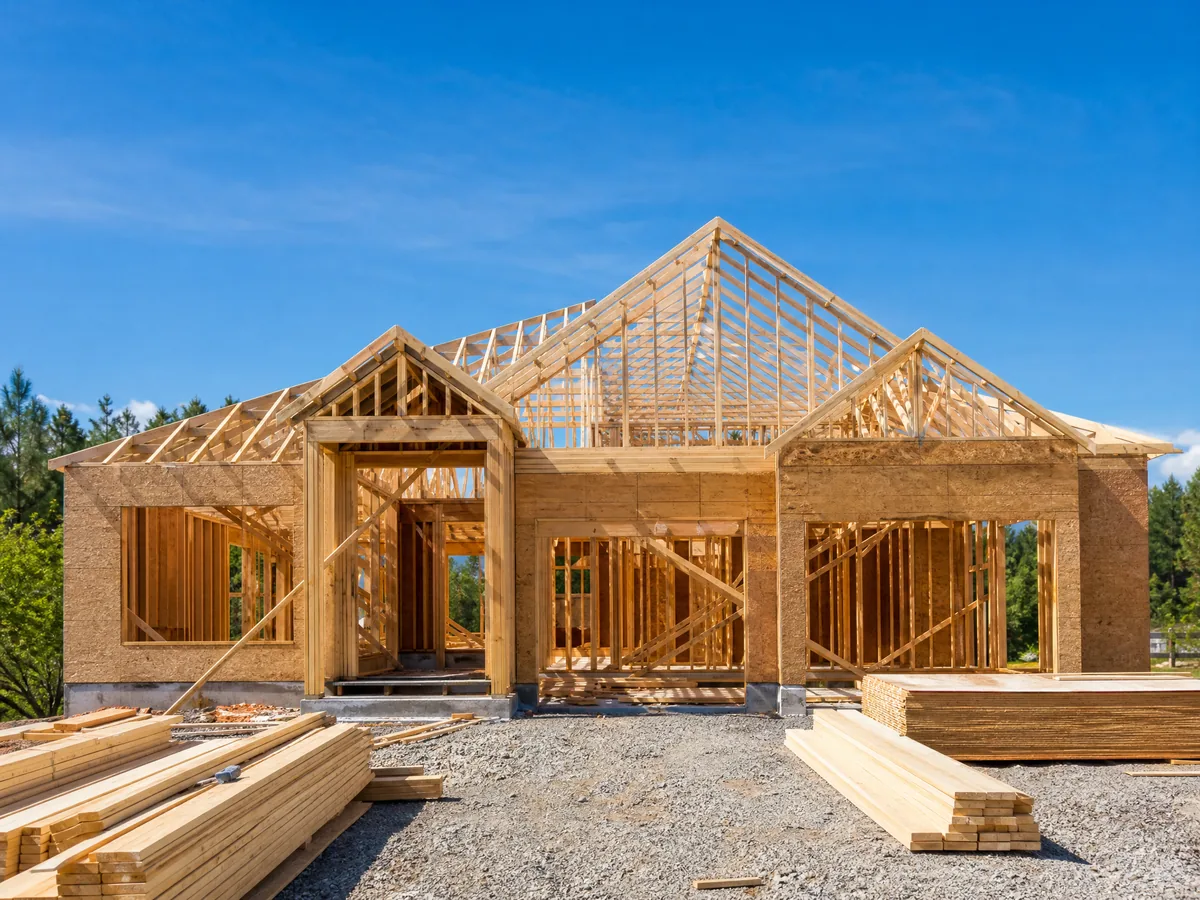
Ground-Up Construction in Stockton, CA from USA Mortgage
70%
max LTV
85%
of cost
Most states
funding
$5M
max loan

Typical figures, subject to underwriting and market conditions. Not a commitment to lend.

How it works

We finance both the land and the vertical construction, with a draw schedule built around your timeline. Experienced builders can access higher leverage on cost.

Who it's for
Spec home builders
Developers and operators
Lot purchase or teardown
Build-to-rent strategies
Typical terms
Loan amountUp to $5M
LeverageUp to 70% LTV / 85% LTC
Term12 to 24 months
DrawsPer build schedule
RateFrom 10.00%*
UseSpec or build-to-rent
Apply now

*Typical terms, subject to underwriting and market conditions.

Run your Ground-Up Construction numbers.

Pressure-test the deal in seconds with our free construction loan calculator, no sign-up required.

Open the Construction Loan calculator
Local FAQ

Ground-Up Construction in Stockton, answered.

Does building in Stockton mean clearing extra flood-related approvals?
It can, and it is state law, not a local quirk. Under SB 5, cities and counties in the Sacramento-San Joaquin Valley cannot approve a development agreement, discretionary permit, or subdivision on land in a flood hazard zone without a finding that the property reaches the 200-year urban level of flood protection. Stockton adopted its SB 5 changes effective July 2016. Confirm early whether your parcel sits in a mapped flood hazard area, since the finding requirement attaches to the zone, not the neighborhood.
How tight is the supply of buildable lots in San Joaquin County?
Tighter than the population growth would suggest. San Joaquin County single-family building permits fell 33.2% in 2025, from 3,773 units to 2,520, even as the county added 44,581 residents since 2020, the second-fastest growth rate of any large county in California. A builder who can secure a lot and move is working against a shrinking permit pipeline, not a shrinking market.
What is the Mossdale Tract levee impact fee, and does it apply to my build?
It applies if you're building in Lathrop, southwest Manteca, or the Weston Ranch area of Stockton. Lathrop, Manteca, Stockton, and San Joaquin County all collect this regional flood-protection impact fee as a condition of issuing a building permit inside the program area, and remit it to the San Joaquin Area Flood Control Agency. The fee is acreage-based and set by a nexus study, so we cannot quote a dollar figure here. Price it from the nexus study before you close on land.
How long does Stockton take to review a ground-up construction permit?
Around 15 working days for a first review on a new single-family home, 20 for new multifamily, plus a resubmittal round if plan check kicks anything back. The city's own timeline sheet, revised May 2026, calls these estimates that can move with staff workload, and larger or more complex projects run case by case. Initial submittals go through Electronic Plan Check and cannot start through the online portal; the first package has to be delivered in person or emailed to the plan check desk.
How does the construction loan term account for the SB 5 flood-protection finding and the RD 17 2028 deadline in Lathrop, Manteca or Weston Ranch?
Structure the draw schedule and the loan term around the entitlement timeline, not just the build schedule. In Lathrop, southwest Manteca and the Weston Ranch area of Stockton, the levees protecting the Mossdale Tract do not yet meet the state's 200-year urban level of flood protection standard, and AB 838 set a statutory deadline of 2028 for Reclamation District 17 to get there. In the meantime, development approvals in that footprint run on annual adequate-progress findings from the local flood management agency rather than a one-time entitlement. If your parcel sits in that footprint, confirm where the current adequate-progress finding stands before you lock a construction timeline, and build slack into the loan term for a permitting step that runs on the government's calendar, not the job site's.
How much cash do I need to bring to a Stockton ground-up build?
Roughly 15% of total project cost. We fund up to 85% of cost and up to 70% of value, whichever binds first. On a $1,000,000 Stockton project that is up to $850,000 from us and $150,000 from you (1,000,000 x 85% = 850,000), released on draws against the build schedule rather than in one advance at closing. Hold something back for the permit cycle, which the city itself calls an estimate that moves with staff workload. Subject to underwriting.
Do you check credit on a Stockton construction loan?
We run credit, but there is no minimum score on this program. A ground-up loan is asset-based, so credit weighs far less than it would at a bank, and a weaker file is usually offset with lower leverage instead of a decline. There is no hard credit pull to start, and no W-2s or tax returns are required. The budget, the schedule and the finished value do most of the work. Subject to underwriting.
How large a Stockton construction loan can I get, and does builder experience change the leverage?
Up to $5 million, and yes, experience moves the leverage. The program runs up to 70% LTV and 85% LTC on a 12 to 24 month term, and experienced builders can access higher leverage inside those limits. Pick the term against the entitlement calendar, not just the build calendar, since a discretionary approval on a flood-hazard parcel in this valley can require a state flood-protection finding before ground breaks. Subject to underwriting.

More Ground-Up Construction questions, answered on the program page

Resources

Guides for Ground-Up Construction

Browse all guides
More in Stockton

Other programs in Stockton

All Stockton loan programs
About the local figures on this page

Local rules move. Every tax rate, fee, ordinance and market figure here comes from a primary source and carries the date we read it, and we correct them as the rules change. Where a number is mid-change or we could not verify it, we say so rather than guess. Before you commit a budget, confirm anything that drives it with the city or county, and talk to your attorney or CPA on questions of law or tax.

Published by USA Mortgage Funding, LLC, NMLS #152588. Researched from primary sources by our team, drafted with AI assistance, and every figure checked against its source before publishing. Where an answer rests on a public record, that record is linked under it. Figures read on 2026-08-22.

Funding Stockton deals fast.

Get real terms, usually same day. No obligation, no hard credit pull to start.

Apply nowTalk to us